Why SBA loans are harder for a startup than for an established business #
An SBA loan is not really a loan from the Small Business Administration. The SBA guarantees part of a loan that a bank or other approved lender makes to you. That guarantee lowers the lender's risk, which is why SBA loans can have longer terms and lower rates than many alternatives. It is also why the lender is careful about who gets one.
Lenders look backward. They want to see what your business has already done: sales, tax returns, bank statements, how you paid your bills. A startup has none of that, or very little. So the lender leans harder on your personal credit, your savings, your experience and your plan. Those are real factors, but they take longer to check and they make the decision slower.
If you have no revenue yet, you are not automatically shut out. You are simply asking for money against a forecast, and most of the work is proving the forecast is believable.
Who can qualify: credit, collateral, experience and the business plan #
The SBA's own guidance says the agency works through lenders who decide on each application. There is no single checklist that guarantees approval, but the same four things come up again and again.
Personal credit. Your personal credit history matters a lot when the business has none. Lenders review it closely, and a recent late payment or high balance can slow a file down or sink it.
Collateral. Many SBA loans ask for collateral, meaning business or personal assets the lender can claim if you default. Some startups have little to pledge. If that describes you, read about business funding without collateral before you plan around an SBA loan, because not every option requires it.
Experience. Lenders want to see that you have done this kind of work before, even if you have not owned a company. Years in the same trade, management roles or a relevant certificate all help.
The business plan. A useful plan answers four questions: what you sell, who pays you, what it costs to deliver, and how the loan gets repaid. Show a realistic monthly cash flow forecast. Overly optimistic numbers hurt you, because the lender will test them.
Owners with a significant stake in the business usually sign a personal guarantee. That means if the business cannot pay, you are personally on the hook. We cover this in more detail below.
What an SBA loan really costs and how long it takes #
The SBA sets maximum amounts and terms for each program, and it sets limits on what lenders can charge. Within those limits, your lender decides your rate. Most SBA loans also carry an upfront guarantee fee that is passed through in the loan cost. Ask for the full cost in dollars, not just the rate.
The table compares the main options a startup usually looks at. Costs are described in plain terms because they depend on your lender, your credit and your file.
| Option | Typical cost | Speed | What it needs |
|---|---|---|---|
| SBA 7(a) loan | Interest set by the lender within SBA limits, plus the SBA guarantee fee | Usually weeks to months | Business plan, personal guarantee, solid personal credit, owner equity |
| SBA microloan | Interest set by the nonprofit lender; loans up to $50,000 | Varies by the local nonprofit | Business plan and a relationship with the lender |
| Bank term loan | Interest rate; often the lowest cost in this table | Usually weeks; slower for a new firm | Operating history, tax returns, often collateral |
| Business line of credit | Interest only on the amount you draw | Slow to approve; fast to draw once open | Revenue history and good credit |
| Short-term business loan | Fixed fee set by a factor; for example, 1.25 over 8 months ≈ 65–75% APR | Often days | Recent bank statements and steady sales |
| Revenue-based financing | Share of future sales; total cost depends on sales and term | Often days | Monthly revenue you can document |
Read the last two rows closely. A factor is a multiplier, not a rate quoted the way interest is. At a 1.25 factor, you repay 1.25 times what you borrowed, and the time you take to repay sets the annual cost. For example, 1.25 over 8 months works out to roughly 65–75% APR. Before you sign, get the APR-equivalent in writing.
The timeline is the real constraint. Plan on several weeks at minimum for an SBA loan, and longer if your file has gaps.
Where startups get turned down, and what to fix first #
Most startup denials are not mysteries. They come from a short list of problems, and most of them can be fixed before you apply.
Thin or damaged personal credit. Pull your personal credit report, check it for errors, and pay down balances if you can. This is often the fastest improvement you can make.
An unrealistic plan. If your projections assume a sales curve no lender would believe, rebuild them. Use conservative numbers and show how the loan gets repaid from cash you can actually forecast.
No cash of your own in the business. Lenders like to see that you have put your own money at risk. If your savings are going into the business, document the transfers.
Messy records. A startup with no bookkeeping looks risky even when the business is sound. Set up a separate business bank account, track every sale and expense, and keep your receipts. Free SBA-supported counseling through local Small Business Development Centers can help you prepare a financing request and tighten your numbers.
If you are denied, ask the lender what the reason was. Then fix that one thing, rather than reapplying with the same file and hoping for a different result.
Faster options when you cannot wait for an SBA decision #
If the cash gap is already here, an SBA loan is probably the wrong tool. Faster options exist, and they cost more.
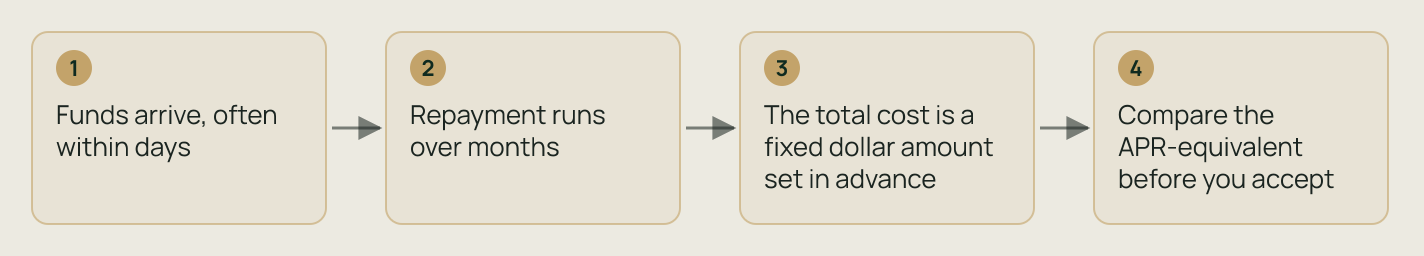
A quick option is short term business loans. They usually pay out in days and are repaid over months. Their cost is a fixed dollar amount set in advance, usually by a factor. For example, a 1.25 factor over 8 months ≈ 65–75% APR. That predictability is useful, but the annual cost is high. Compare the APR-equivalent before you accept any offer.
Revenue-based financing ties your repayment to your sales. In a slow month you pay less; in a strong month you pay more. That can help a young company, but it also means the total cost is harder to predict. Ask how the repayment percentage is calculated and when the obligation ends.
Some startups also consider unsecured business loans. These skip collateral, so they can move faster, but they usually come with higher rates or shorter terms. Read the full cost before you compare.
Whatever you choose, ask for the total dollars you will repay, the payment schedule, and what happens if you pay early or miss a payment. Some states now require a signed cost disclosure before a commercial financing offer becomes final. Use that disclosure to compare offers side by side.
A factor of 1.25 on $50,000 over 8 months is a real cost, even though the factor itself looks like a small number. The steps below show how the loan moves from funding to final payment.
Can a brand-new business get an SBA loan? #
Yes, in principle. The SBA does not require a minimum operating history for every program, and lenders do approve some new businesses. But a brand-new business faces a harder review. Lenders will weigh your personal credit, your equity, your experience and the quality of your plan more heavily than they would for an established company. Expect a longer process and more questions. A new business with strong personal credit, real savings invested and a conservative plan has a better chance than one that depends on projected sales alone.
How long do SBA loans for startup business take? #
For most startups, plan on several weeks at least, and often longer. The time goes into assembling documents, answering the lender's questions, and waiting for the SBA's review when the loan is guaranteed. Files with gaps in credit history or missing financial statements take longer. If you need money within a few weeks, an SBA loan alone will probably not meet that deadline. Start the file early, or use a faster option for the immediate gap and pursue SBA funding in parallel.
Do SBA loans for startups require a personal guarantee? #
Usually, yes, at least from owners with a significant stake in the business. A personal guarantee means that if the business cannot repay the loan, you are personally responsible for the balance. Read the guarantee carefully before you sign, and ask whether it is unlimited. Also check whether the lender can pursue your personal assets. A guarantee is not a formality. It is a personal financial commitment, and it should be treated like one.
What should I do if my startup is denied an SBA loan? #
Ask the lender for the specific reason, and get it in writing if you can. Then fix that problem before reapplying. Common fixes include cleaning up personal credit, tightening the business plan, documenting your own cash invested, and setting up basic bookkeeping. A free SBA-supported counselor at a local Small Business Development Center can review your file with you. Meanwhile, do not let a denial leave you without options. Line up a faster source for the cash you need now, so one decision does not decide your whole year.
Is an SBA loan cheaper than a merchant cash advance for a startup? #
Almost always, yes, when you compare the total dollars and the annual cost. SBA loans carry interest rates and fees set within program limits, and their terms are typically longer. A merchant cash advance is priced with a factor and repaid quickly. For example, 1.25 over 8 months ≈ 65–75% APR, which can be a very high annual cost. The tradeoff is speed and approval. A merchant cash advance can fund quickly when an SBA loan would not. Compare the APR-equivalent of each offer, and read the agreement's repayment and default terms before you accept.
Matching the money to the month you are in #
An SBA loan is a good fit when you have time, a clean file, personal credit you can stand behind, and a plan that a lender can test. It is also the right tool when you want the lowest cost and the longest term, and you can accept a personal guarantee. It is not the right tool when you need cash this month, when you have no documented plan, or when you cannot take on a personal guarantee.
For a cash gap that cannot wait, a short-term or revenue-based option may be the honest answer, provided you know the full cost and can cover the repayments from cash flow. Use the faster option to bridge, and keep building the file for SBA funding.
Next step: start your request when your file is ready, or sooner if the gap is already here and you need to compare real offers.
Sources #
Everything in this guide is general information, and not advice about your situation. All figures given are illustrative; the only terms that apply to you are those in the agreement you sign. What we do and where our fee comes from.